

Video PD (video personal discussion) is a live, recorded video call in which a lender's credit officer interviews a loan applicant to judge whether they can repay. The officer asks about work or business, income, expenses, existing loans and the use of the loan, and sees the home or business premises on camera. It replaces or adds to a field visit. It is a credit step, not identity KYC.
This guide is for credit, risk and product teams at NBFCs, housing finance companies and banks, and for the engineers who build their loan journeys. It covers what a Video PD call contains, which RBI and data protection rules touch it (and which do not), a checklist by loan type, fraud controls, and tested code for the video layer.
Key takeaways
- Video PD is the personal discussion step of credit appraisal done over video: the officer tests the applicant's income, business and repayment capacity, not their identity.
- No RBI Direction that VideoSDK searched names or requires a personal discussion. PD is a lender credit practice; the RBI requires a proper assessment of creditworthiness, and PD is one way to do it.
- If the same session also does KYC, VideoSDK's reading is that the whole session falls under the V-CIP controls, including the rule that the technology provider retains no data. Running the PD as its own session keeps the two apart.
- In a digital lending journey, the lender's app may take one-time camera, microphone and location access only for onboarding or KYC, with explicit consent (Credit Facilities Directions, 2025, para 13(1)). Credit appraisal is not named, so take separate consent for a PD call (VideoSDK's reading). Store the data on servers in India (para 14(4)).
- A good Video PD records the call, the location, photos of the premises and documents, and a written PD report that a person signs. An AI summary is a draft for that report, not the report.
What does Video PD mean?
Video PD is the video form of the personal discussion (PD), the interview a credit officer holds with a loan applicant before a loan is sanctioned. In a physical PD the officer visits the applicant's home or place of work. In a Video PD the same conversation happens on a recorded video call, and the applicant shows the premises with the phone camera.
Lenders use PD where documents alone do not show the full picture. Axis Bank's home loan guide says the bank may call most salaried applicants for a phone discussion, and may visit self-employed applicants at their place of work to understand the business. A loan advisory guide from Naskar Finserv describes the same scaling: a PD can be by phone, in person or by video, and its depth depends on the applicant's profile and the product.
What does PD stand for in a loan?
PD in a loan file means personal discussion. Credit teams also use "PD" for probability of default, a risk model output, and outside lending "PD" often means USB Power Delivery for phone chargers. In Video PD, PD always means the personal discussion with the applicant.
Where PD fits in the loan process
The personal discussion sits between the documents and the decision. The applicant applies and submits documents, KYC is completed, and the lender pulls the bureau report and bank statements. Then the credit officer holds the PD, writes the PD report into the credit file, and the approver decides on sanction. A PD can also happen again before disbursement or for a top-up loan.
Where lenders use Video PD
Our summary of lender PD sheets and vendor pages (for example Gridlines' guide to Video PD for loans and VideoCX's SMFG India Credit case study) shows Video PD used for:
- Home loans and loan against property (LAP), where the officer checks the residence, the property and the source of the down payment.
- Business loans and MSME loans, where the officer sees the shop, office or factory, the stock and the staff.
- Personal loans for self-employed applicants, and high-value personal loans for salaried applicants where policy asks for a discussion.
- Pre-disbursement checks and top-up loans, where the officer confirms that nothing material has changed.
Video PD vs Video KYC (V-CIP)
Video KYC confirms who the applicant is. Video PD tests whether the applicant can repay. The two can run in one call, but they answer different questions and follow different rules.
| Point | Video KYC (V-CIP) | Video PD |
|---|---|---|
| Question it answers | Is this the person they claim to be? | Can this person repay this loan? |
| Rule that governs it | V-CIP in the RBI KYC Directions, 2025 (NBFCs: para 26 and 27 of RBI/DOR/2025-26/361) | The lender's credit policy |
| Who runs it | A specially trained official (para 27(2)(i)) | A credit officer or credit manager |
| What it checks | Identity document, face match, liveness, live GPS location (para 27(1)(iv) and (v)) | Work or business, income, expenses, loans, end use, premises |
| Outcome | Customer due diligence done or not done | Approve, downsize, reject or refer for a field visit |
The RBI NBFC KYC Directions, 2025 list the uses of V-CIP in para 26: customer due diligence for new customers, conversion of accounts opened with Aadhaar OTP e-KYC, and KYC updation. Credit appraisal is not on that list. The closest V-CIP clause is para 27(2)(x), which asks the NBFC to confirm "the economic and financial profile" the customer submitted. A V-CIP call therefore touches the applicant's finances, but it does not replace a PD.
For the full set of V-CIP rules an NBFC must meet on the KYC call itself, see our guide to V-CIP rules for NBFCs.
VideoSDK's reading: if the same call also performs V-CIP, treat the whole call as inside the V-CIP controls (see our clause-by-clause guide to the RBI V-CIP rules). That includes para 27(1)(i): a cloud or third-party technology provider "shall retain no data", and the recording moves to the lender's own servers as soon as the V-CIP is complete. A vendor transcript or summary of a combined call would sit against that rule, so we suggest running the PD as its own session when you want transcription. Some vendors, such as Gridlines, describe both in one session; ask your compliance team which way your policy goes. For the KYC call itself, see what V-CIP is and how the call works.
Is Video PD mandatory?
No RBI Direction requires a Video PD, but a lender's own credit policy can require one. Four sets of rules touch a recorded PD call: digital lending, the DPDP Act, outsourcing, and telling the borrower the call is recorded. They are set out in the rules section below.
How a Video PD call works, step by step
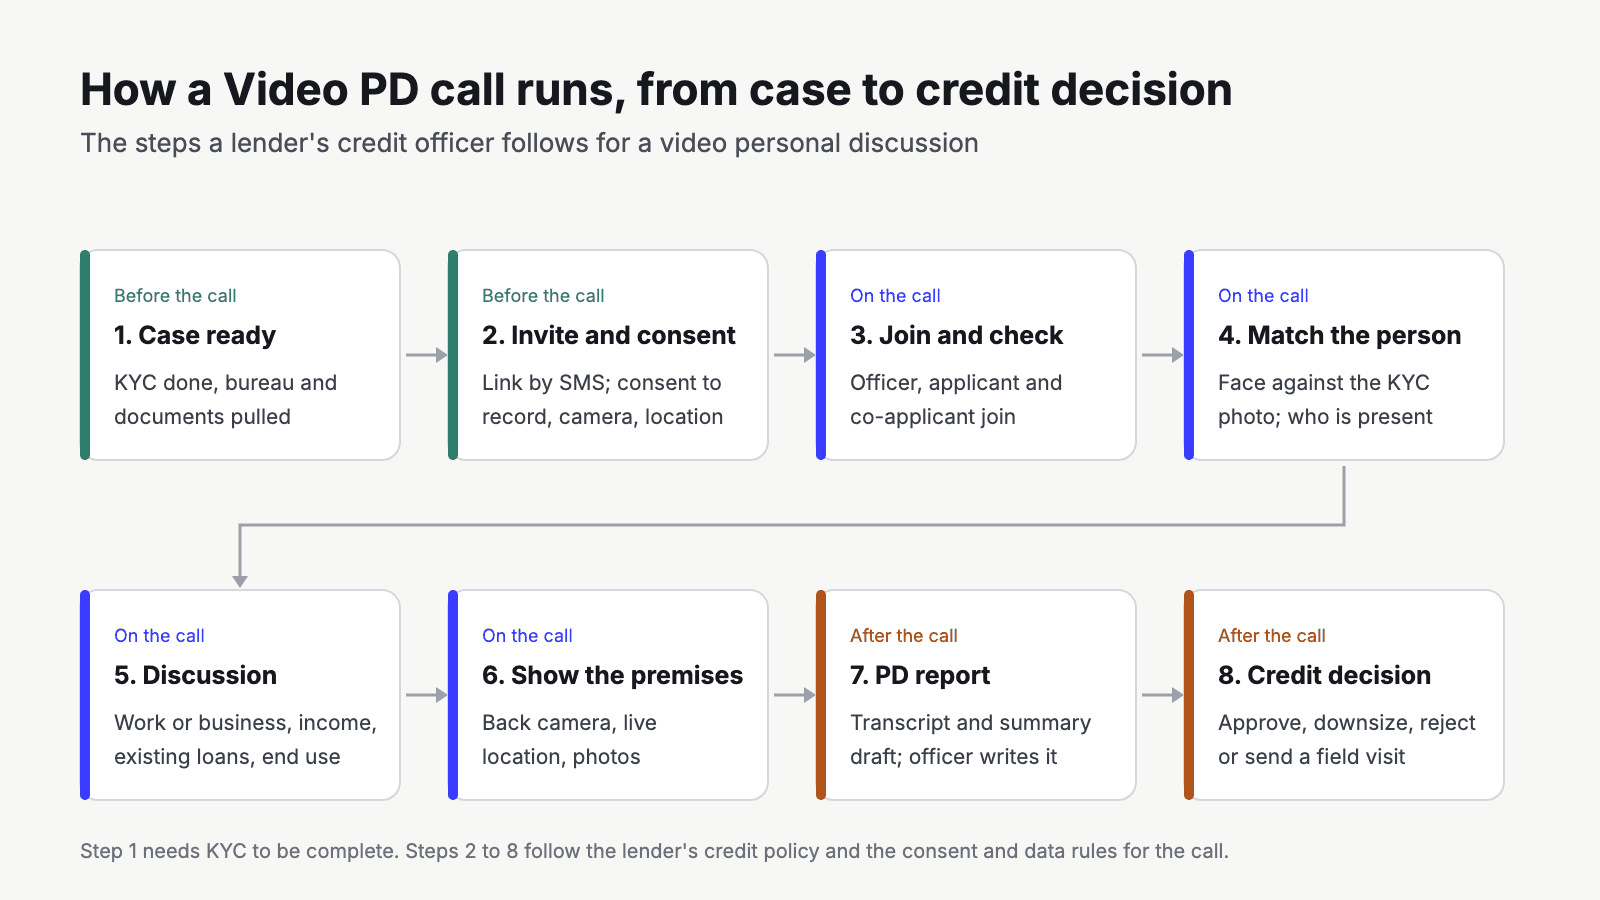
A Video PD call follows the lender's credit policy. The eight steps below are a typical flow, assembled from lender PD sheets and the vendor flows described by Perfios, Melento and the SMFG case study.
- Case ready. KYC is complete (or booked as a separate V-CIP session), the bureau report and bank statements are pulled, and the credit officer has the application and a list of points to test.
- Invite and consent. The applicant gets a link by SMS or email with a time slot. Before joining, the page shows the notice and asks for consent to record the call and to use the camera, microphone and location.
- Join and check. The credit officer, the applicant and any co-applicant or guarantor join. A pre-call check flags poor network quality before the call (see how to keep video calls working on weak networks).
- Match the person. The officer compares the face on the call with the KYC photo and notes who else is present. A loan agent or DSA (direct selling agent) should not answer for the applicant.
- Discussion. The officer asks about work or business, income, household expenses, existing loans and the use of the loan, and compares the answers with the documents.
- Show the premises. The applicant switches to the back camera and walks through the shop, office, factory or home. The page shares the live location, and the officer takes photos of the signboard, stock and any document shown.
- PD report. After the call, the officer writes the PD report. A transcript and an AI summary can give a first draft, but the officer checks every figure and signs the report.
- Credit decision. The case goes to the credit approver with the report, the recording and the photos: approve, downsize, reject or send a field visit.
What does a credit officer ask in a Video PD?
A credit officer asks about the five things that decide repayment: who the applicant is, how they earn, what they spend and owe, why they want the loan, and what backs it. The checklist below groups the questions by loan type, drawing on lender PD sheets, the practitioner and DSA guide from Mudrahome and the SMFG case study linked above. The camera column is VideoSDK's own judgement of what video can show, not a lender requirement.
| Loan type | What to ask | What to see on camera |
|---|---|---|
| Every loan type | Existing EMIs and FOIR, bank account behaviour (average balance, bounced cheques), anything on the bureau report, years at the current address, references where policy asks | The applicant alone, in the place they say they live or work |
| Salaried personal loan | Employer and type (government, public sector, private limited), role, years in job, take-home pay, other income, family and dependents, existing EMIs, end use | Office ID or salary slip held up to the camera; the applicant at home or at work, alone |
| Self-employed and MSME business loan | Years in business, constitution, products, main customers, credit terms, turnover declared and actual, margin, GST status, staff count, other loans, expansion plans | Signboard with the address, the shop or factory floor, stock and work in progress, machinery, staff present, GST certificate or licence on the wall |
| Home loan | Property being bought, seller, agreement value, source of the down payment, self-use or investment, current residence owned or rented, household income | Current residence; the property if the applicant is at the site; the agreement or allotment letter |
| Loan against property (LAP) | Property owner and title, who lives there, end use in detail, business cash flow that repays the loan | House number and nameplate, the property inside and outside, the neighbourhood |
| Top-up or balance transfer | Use of the earlier loan, repayment record, why the top-up is needed now, any change in income | Same as the original loan type, focused on what changed |
The officer closes the discussion with a recommendation: approve, downsize, reject or refer. The same PD sheets record that decision with the officer's name.
What goes into a PD report
A PD report sits in the credit file and feeds the Credit Appraisal Memo (CAM) that the approver reads. Our suggested structure, drawn from lender PD sheets and practitioner templates:
- Case details: applicant, co-applicants, loan type and amount, date, time and mode (video).
- Profile: family and dependents, residence, education and work history.
- Income and business: what was declared, what was seen or heard, and any gap between them.
- Obligations: existing EMIs, FOIR and banking behaviour.
- End use and repayment source.
- Premises and collateral observations, with photo references.
- The officer's observations, risks, and the recommendation, signed.
A PD report skeleton (placeholders, not real data):
Applicant: [name]          Loan type: [type]          Amount requested: [amount]
Declared: monthly income [amount] from [employer or business]
Seen or heard on the call: [what the officer saw]; match with documents [yes / partly / no]
Gap between declared and seen: [difference, if any]
Obligations: existing EMIs [amount]; FOIR [percent]
Premises: [photo references]
Recommendation: [approve / downsize / reject / refer for field visit]; signed [officer name]
What to record in a Video PD, and why
A Video PD is only useful if the evidence survives the call. The credit approver, internal audit and, for a digital loan, the para 8(1) audit record all depend on it. Keep these items with the loan file:
| Evidence | How to capture it on video | Why it matters |
|---|---|---|
| Consent and notice | Consent screen before joining, plus the applicant's spoken yes at the start of the recording | Credit Facilities para 13 for digital loans; DPDP Act sections 5 and 6 from May 2027 |
| The full call | Composite recording of all participants, stored in India | Lets the approver and auditor check the PD report against what was said |
| Location | Live location shared from the applicant's browser, and the time of the call from the session record | Gives the officer a location to compare with the address on file; a browser location is a record, not proof |
| Premises and documents | Back camera walk-through, plus still photos of the signboard, stock and documents | Evidence that the business or property exists as described |
| Who was present | Participant list with join and leave times | Shows whether anyone else was on the call or prompted answers |
| PD report | Written by the officer, with the transcript or summary as a draft | The document the credit decision rests on; can serve as the para 8(1) record |
When a field visit is still needed
Video PD reduces field visits, but it does not remove them. Send a field visit, or add a technical valuation, when:
- The video is too poor to see the premises, or the applicant will not switch to the back camera.
- The live location does not match the address on file, or the premises look borrowed (no signboard, no stock, staff who do not know the owner).
- The loan is against property, where a technical and legal check of the property is usually still needed whatever the call shows.
- The loan funds construction. A PD before sanction can be on video, but para 192 of the HFC Directions expects "physical verification/ project progress monitoring with proof (snap shots)" for construction loans, so plan site checks into the disbursement stages.
- The applicant is a first-time business borrower with no books, and the credit policy asks for a physical visit at that loan size.
Fraud controls for a Video PD
A Video PD has the same weak points as any remote check, plus some of its own. Build these controls into the call flow:
- Prompting by the loan agent. Ask the applicant to be alone, ask the agent to leave the frame, and note anyone else heard on the call. Switch to open questions when answers sound read out.
- A pre-recorded or fake video. Match the face against the KYC photo. Then ask for things a recording cannot do: point the back camera at a named object, read out the top invoice, walk to the door.
- Borrowed premises. Ask staff by name, look for the business name on the signboard and invoices, and compare the live location with the GST or utility address.
- Face-swap or AI-generated video, and virtual cameras. A real-time deepfake can follow spoken instructions, so a request to point the camera at an object does not rule it out. Liveness and spoof checks belong in the KYC step, before the PD. In the PD, an officer who doubts the video should stop and send a field visit.
- Location spoofing. A browser location can be faked. Compare it with the address, the network the call comes from and what the camera shows; for KYC calls the V-CIP rules also require the application to be capable of preventing connections from IP addresses outside India (para 27(1)(iii)).
- A gap in the recording. Configure the recording so the call ends if the recording stops and cannot recover, and start a fresh session after a call drop.
- Copying errors. Push the recording, transcript and photos to the loan system by API instead of pasting links by hand.
Which rules apply to a recorded Video PD call?
No RBI Direction names a personal discussion. VideoSDK searched these texts for "personal discussion", "personal interview" and "PD" and found none:
- the Housing Finance Companies Directions, 2025;
- the NBFC and Commercial Banks Credit Facilities Directions, 2025;
- the Responsible Business Conduct Directions, which hold the Fair Practices Code;
- the MSME lending Master Direction;
- the KYC and outsourcing Directions.
We did not search NHB circulars outside the RBI's consolidated set.
What the RBI does require is a real credit assessment. The Commercial Banks Responsible Business Conduct Directions, 2025, para 332, say a bank "shall ensure that there is proper assessment of credit application of the borrower" and shall not use security as a substitute for due diligence. For housing finance companies, para 190 of the RBI Housing Finance Companies Directions, 2025 says the HFC "shall review and strengthen their credit appraisal systems". PD is one way a lender meets these duties, and the lender's own credit policy decides when a PD is needed and whether video is enough.
Four sets of rules do touch a recorded Video PD call. The first applies only where the loan is a digital lending journey as the Credit Facilities Directions define it; check with your compliance team whether a branch-assisted or offline PD falls inside.
1. Digital lending: app permissions, consent and storage in India
The digital lending rules moved on 28 November 2025. The RBI (Digital Lending) Directions of 8 May 2025 were repealed (RBI/2025-26/100, entry 43 in the annex of withdrawn circulars), and their text now sits in Chapter III of each entity's Credit Facilities Directions, 2025. For NBFCs, including housing finance companies, that is the RBI (Non-Banking Financial Companies - Credit Facilities) Directions, 2025 (RBI/DOR/2025-26/347). For banks it is the Commercial Banks - Credit Facilities Directions, 2025 (RBI/DOR/2025-26/154).
| Para | What it says | What it means for a Video PD |
|---|---|---|
| 8(1) | Obtain the borrower's economic profile, "at a minimum, age, occupation and income details", and keep it on record for audit | Where the PD captures these details, the PD report can serve as that record (VideoSDK's reading) |
| 13(1) | No access to "file and media, contact list, call logs, telephony functions"; "a one-time access can be taken for camera, microphone, location or any other facility necessary for the purpose of on-boarding / KYC requirements only, with the explicit consent of the borrower" | Ask for camera, microphone and location for the call only, with explicit consent, and never ask for contacts or files |
| 13(2) to 13(4) | Borrower can give or deny consent for specific data, limit sharing and retention, revoke consent; the purpose is disclosed at each stage; explicit consent before sharing personal data with a third party | Tell the applicant why the call is recorded and how it is used, and take consent before the recording goes to anyone outside the lender |
| 14(4) | "all data is stored only in servers located within India"; data processed outside India is deleted there and brought back within 24 hours | Store the recording, photos and transcript in India |
Para 13(1) names onboarding and KYC as the purposes for one-time camera access. A PD can be read as part of onboarding a borrower, but the clause does not name credit appraisal. VideoSDK's reading: take separate, explicit consent for the PD call and its recording, and do not rely on a standing app permission. Check this with your compliance team.
2. The DPDP Act and Rules: notice and consent
Under the Digital Personal Data Protection Act, 2023 the lender is usually the Data Fiduciary and the video platform a Data Processor. The DPDP Rules, 2025 were notified on 13 November 2025 (G.S.R. 846(E)). The notice, consent and erasure duties in sections 5 to 8 of the Act come into force eighteen months after that date, so from May 2027 unless MeitY changes the schedule (commencement notification G.S.R. 843(E) on MeitY's site).
For a Video PD that means three things. Give a notice before the call that lists what is captured (video, audio, location, documents shown, statements about income) and why. Take consent that is "free, specific, informed, unconditional and unambiguous" (section 6(1)), with an easy way to withdraw it. Erase the data once the purpose ends, unless another law requires the lender to keep the record (section 8(7)).
The Act's own illustration to section 5(1) uses a "live, video-based customer identification process" as its example of a request that needs prior notice. The Act's illustration to section 8(7) shows a bank keeping records "for a period of ten years beyond closing of accounts" because a law requires it. VideoSDK's reading: a PD recording that forms part of the loan record is kept for the period your record-keeping rules set, then erased. Build the notice and consent screen now, so the flow does not change in 2027.
3. Outsourcing: your video vendor is a service provider
If a third party runs the video layer, the RBI Managing Risks in Outsourcing Directions, 2025 apply. For NBFCs, para 74 of the RBI Managing Risks in Outsourcing Directions for NBFCs, 2025 (RBI/DOR/2025-26/363) lists the minimum terms for an IT services outsourcing contract. They include the NBFC's access to "all data, books, records, information logs" and "storage of data only in India (as applicable)". The bank Directions have the same terms in para 69. Ask your vendor for these terms before the first PD call.
4. Recording a call: tell the borrower
We found no RBI rule that sets how to record a PD call, but the RBI has a precedent for recorded calls. Para 442(4) of the Commercial Banks Responsible Business Conduct Directions requires recovery calls to be recorded and asks banks to take precautions "such as intimating the customer that the conversation is being recorded". The Housing Finance Companies Directions have the same rule for recovery calls in para 170(vi). Do the same at the start of every Video PD: say that the call is recorded and why, and capture the applicant's answer in the recording.
What to tell applicants before a Video PD call for a loan
Applicants who know what the call covers can prepare for it. Share guidance like this with the invite:
- Join from your home or business premises, not from the loan agent's office, so you can show the place on camera.
- Use a phone with a back camera, a charged battery and a steady network. Good light helps the officer see documents.
- Keep your ID, salary slips or business documents, bank statements and the property papers within reach.
- Answer for yourself. The officer will ask the agent or DSA to step away if they speak for you.
- Know your numbers: monthly income, household expenses, existing EMIs and the loan amount you need and why.
Tell applicants the slot length you have booked; it depends on the loan type and on whether a premises walk-through is needed.
What is Video PD software, and how do you build it?
Video PD software is the tool a lender uses to run a personal discussion with a loan applicant over a recorded video call. It joins the officer and the applicant, switches to the back camera for the premises walk-through, records the call with location and time, and passes the recording and notes to the loan system. Lenders either buy a ready vendor platform with its own screens and workflow, or build the flow on a video SDK such as VideoSDK inside the loan journey they already run. Building fits teams that want the PD inside their own app and loan system.
A Video PD flow needs five things from the video layer:
- A browser call that several people can join.
- A camera switch for the premises walk-through.
- A recording that closes the call if it fails.
- Photos and location during the call.
- The recording and notes in a form the loan system can pull.
VideoSDK provides the SDK methods, REST APIs and webhooks for each; the loan system integration is yours.
| Video PD need | VideoSDK feature | Note |
|---|---|---|
| Officer, applicant, co-applicant and guarantor on one call | A room that several participants join (concepts and architecture) | Runs in the browser with the React or JavaScript SDK |
| Network check before the call | Pre-call check | Checks the camera, microphone and network quality before the officer joins |
| Premises walk-through | Camera controls and optimize video tracks (changeWebcam, createCameraVideoTrack) | Code below |
| Photos of stock and documents | Image capture | Captured files sit in temporary storage and are deleted when the meeting ends; save them to your own storage during the call |
| Live location | PubSub topic plus the browser's geolocation (a tested location sample is in the RBI V-CIP guide linked above) | Shown to the officer; a custom recording template can render the coordinates as a watermark |
| Recording that closes the call if it cannot recover | Start recording API with onFailure | Code below |
| Recordings in your own cloud | Recording storage configuration for AWS S3, Azure Blob or GCP | A bucket in an Indian region keeps the stored file in India; where media is processed is a separate question (see Geo Fencing below) |
| Transcript and summary draft | Post transcription and summary | Code below |
| Who joined and when | Sessions API | Participant join and leave times for the file |
| Media servers in India only | Geo Fencing to the INDIA region | Listed under Enterprise in the docs; ask our team about your plan |
| Officer's console | Lobby, admit and reject, participant controls (agent dashboard guide) | The officer admits the applicant from the lobby |
Two limits to plan for. Recording and transcription do not run while end-to-end encryption is on (E2EE docs), and recording encryption cannot be combined with transcription and summaries. Encryption is set per API key, so a lender can use one key with encrypted recordings and another with transcription, and decide per loan product which one it needs. Also confirm with VideoSDK where transcript and summary files are stored and for how long before you turn transcription on for loan calls, since para 14(4) asks for storage in India.
The samples below use the React SDK @videosdk.live/react-sdk 1.2.0. Each one was type-checked against the SDK's types. The camera sample ran in headless Chrome with a fake camera against a live VideoSDK project; the two server functions ran against the live API on their error and empty paths. The notes under each sample say what we could not run. Token generation stays on your server.
Switch to the back camera for the premises walk-through
The applicant taps one button to show the premises. The page asks the browser for the back camera with facingMode: "environment" and swaps the published video track with changeWebcam. Some phones report which camera opened, so the page can say when only a front camera exists; when the browser reports nothing, it asks the applicant to check the view.
// PremisesCamera.jsx (applicant's phone page, inside <MeetingProvider>)
import { useState } from "react";
import { useMeeting, createCameraVideoTrack } from "@videosdk.live/react-sdk";

export default function PremisesCamera() {
  const { changeWebcam } = useMeeting();
  const [facing, setFacing] = useState("user");
  const [status, setStatus] = useState("");

  async function switchTo(next) {
    try {
      // facingMode asks the phone browser for the back ("environment") or front ("user") camera.
      const track = await createCameraVideoTrack({
        facingMode: next,
        optimizationMode: "detail", // sharper shelves, stock and documents
        encoderConfig: "h720p_w1280p",
        multiStream: false,
      });
      await changeWebcam(track);
      setFacing(next);
      // Some phones report which camera opened; some browsers report nothing.
      const opened = track.getVideoTracks()[0]?.getSettings().facingMode;
      if (next === "user") setStatus("Showing your face.");
      else if (opened === "environment") setStatus("Showing the back camera.");
      else if (opened === "user") setStatus("This device has no back camera. Please turn the phone to show the premises.");
      else setStatus("Camera switched. Please check that the premises are visible to the officer.");
    } catch (err) {
      setStatus("Could not switch the camera. Please try again.");
    }
  }

  return (
    <div>
      <button onClick={() => switchTo(facing === "user" ? "environment" : "user")}>
        {facing === "user" ? "Show my premises" : "Back to my face"}
      </button>
      <p>{status}</p>
    </div>
  );
}
In our test the SDK passed facingMode: "environment" to the browser and the published track changed. With the track's reported camera emulated, each message showed as written: back camera, front camera only, and nothing reported. We could not test a real phone's back camera here. The SDK 1.2.0 types for createCameraVideoTrack accept "user" or "environment", and the SDK passed the value straight to the browser, which uses "user" for the front camera; some docs pages write "front". We first tried to pick the camera from getWebcams() by its facingMode field, but SDK 1.2.0 reported a single desktop camera (a fake device in headless Chrome) as environment, so do not rely on that field to detect a back camera.
Start the recording with a PD summary prompt
Start the recording from your server when the officer is ready. The transcription block asks for a transcript and a summary shaped like a PD report. Per the API reference, onFailure closes the room if the recording cannot start or recover within the wait time, so the call does not carry on unrecorded.
// startPdRecording.mjs (your server; serverToken is a VideoSDK token from your backend)
const PD_SUMMARY_PROMPT = [
  "Summarise this loan personal discussion for the credit officer.",
  "Use these headings: People on the call; Business or employment described;",
  "Income and expenses stated; Existing loans mentioned; What was shown on camera;",
  "Points to verify. Quote amounts exactly as spoken. Do not give a credit decision.",
].join(" ");

export async function startPdRecording({ roomId, serverToken, webhookUrl }) {
  const res = await fetch("https://api.videosdk.live/v2/recordings/start", {
    method: "POST",
    headers: { Authorization: serverToken, "Content-Type": "application/json" },
    body: JSON.stringify({
      roomId,
      webhookUrl, // recording and transcription status events
      config: { mode: "video-and-audio", quality: "med", orientation: "landscape" },
      transcription: { enabled: true, summary: { enabled: true, prompt: PD_SUMMARY_PROMPT } },
      // End the call if recording cannot start or recover within 30 seconds.
      onFailure: { waitTime: 30, action: "close-room" },
    }),
  });
  if (!res.ok) throw new Error(`Recording did not start: ${res.status} ${await res.text()}`);
  return res.text();
}
We ran the error path: on a room with no live session the API answered 403 "No active session found." and the function threw as written. We did not start a real recording, because that is a billed recording on our test account, so the onFailure and summary behaviour follow the docs, not our test.
Fetch the transcript and summary for the PD report
After the call, fetch the transcript and summary files for the room and attach them to the loan file as a draft for the officer.
// fetchPdNotes.mjs (your server): transcript and summary files for one PD room
export async function fetchPdNotes({ roomId, serverToken }) {
  const url = `https://api.videosdk.live/ai/v1/post-transcriptions/?roomId=${encodeURIComponent(roomId)}`;
  const res = await fetch(url, { headers: { Authorization: serverToken } });
  if (!res.ok) throw new Error(`Could not fetch transcriptions: ${res.status}`);
  const { transcriptions = [] } = await res.json();
  return transcriptions.map((t) => ({
    sessionId: t.sessionId,
    status: t.status, // check the status before reading the files
    transcriptTxt: t.transcriptionFilePaths?.txt,
    summaryTxt: t.summarizedFilePaths?.txt,
    recording: t.filePath,
  }));
}
The live API returned pageInfo and transcriptions as documented, and an empty list for rooms with no transcription. The file fields follow the post transcriptions API reference, since our test project had no completed transcription to read.
To compare video KYC API providers, see our video KYC API comparison. If you are weighing a vendor platform against your own build, our build vs buy guide for video KYC infrastructure covers the same choice. To scope a Video PD flow for your loan products, talk to our team.
Glossary
- Credit Appraisal Memo (CAM) is the credit file note that brings together the bureau report, financials, PD report and the recommendation for the approver.
- FOIR (fixed obligation to income ratio) is the share of monthly income that goes to existing EMIs plus the new loan's EMI. Lenders use it to size the loan.
- LAP (loan against property) is a secured loan against a residential or commercial property the borrower owns.
- DSA (direct selling agent) is an agent who sources loan applications for a lender. A DSA should not answer for the applicant in a PD.
Frequently asked questions
What is Video PD in banking?
Video PD in banking is the credit officer's pre-sanction interview held on a recorded video call. Lender and vendor descriptions show it used for self-employed applicants, business loans, home loans and LAP, where a field visit was the usual route. It sits in credit appraisal, so the lender's credit policy governs it, not the V-CIP rules.
What is the difference between Video PD and Video KYC?
Video KYC answers "who is this?" and Video PD answers "can they repay?". The KYC call follows the V-CIP standards, including the rule that a technology provider assisting the V-CIP retains no data. We suggest a separate PD session when you want a transcript of the PD (VideoSDK's reading).
Is Video PD mandatory for a loan?
No RBI Direction requires a personal discussion, by video or in person. The lender's credit policy sets when a PD is needed and whether video is acceptable in place of a visit. Axis Bank, for example, says it may call most salaried applicants and may visit self-employed applicants at work.
Can a co-applicant or guarantor join the same Video PD?
Yes. A Video PD can be a group call in which the credit officer talks to the applicant, the co-applicant and the guarantor together or one after another. This matters on loans where the co-applicant's income or the guarantor's standing is part of the credit decision. Take each person's consent to the recording separately.
Is a Video PD call recorded, and who can see it?
Vendor and lender descriptions, such as the SMFG case study, show the call recorded and kept with the loan file, so the credit approver and auditors can check the PD report. For a digital loan, the Credit Facilities Directions require consent, disclosure of the purpose, and storage on servers in India. From May 2027 the DPDP Act adds a formal notice and the right to withdraw consent.
How long does a Video PD take?
No RBI rule or public source we found sets a length for a Video PD. It depends on the loan type and the depth the credit policy asks for: a salaried applicant's discussion is short, while a business loan with a premises walk-through and stock check takes longer. Book slots per product and track the real call times.
The next step is to map the PD checklist for each of your loan products to the call flow above. To try the camera switch, recording and transcription samples on your own project, create a VideoSDK account; a new account comes with a $20 credit. For Geo Fencing to India-region servers, which the docs list under Enterprise, contact our team.