

The main types of KYC in India are in-person (physical) KYC, Aadhaar OTP e-KYC, Aadhaar biometric e-KYC, offline Aadhaar verification, DigiLocker e-documents, CKYC, digital KYC and video KYC. KYC (Know Your Customer) is how a bank checks who you are before it opens an account, and the RBI KYC Directions, 2025 set which routes a bank may use. Most routes give full KYC. Two kinds of bank account carry caps: one opened by Aadhaar OTP e-KYC without meeting you, and a small account.
Adding video KYC to your bank or fintech app?
VideoSDK gives you the video layer for video KYC (V-CIP): a waiting lobby where your official admits the customer, a geo-tag recording template that shows the coordinates your app sends, and delivery of recordings to your own cloud bucket. A new account comes with a $20 credit.
What are the types of KYC in India?
The RBI does not number the types of KYC; this guide groups the routes its KYC Directions, 2025 allow a commercial bank into eight. Every route also needs your PAN or Form 60 (para 23(5)). An officially valid document (OVD) is one of six: passport, driving licence, proof of possession of Aadhaar, voter ID, NREGA job card or a National Population Register letter (para 5(1)(xiv)). Paragraph numbers are from the commercial bank text; other lenders have their own Directions with different numbers.
| KYC type | How it works | Who uses it, and when | Limits or conditions |
|---|---|---|---|
| In-person (physical) KYC | You show an original OVD at a branch or to a business correspondent, and the bank records it through digital KYC (para 23) | Anyone, for a new account or a KYC update | None; full KYC |
| Aadhaar OTP e-KYC | You give your Aadhaar number and the OTP sent to your Aadhaar-linked mobile; the bank pulls your details from UIDAI, the Unique Identification Authority of India (paras 23 and 25) | Banks, when you choose to share your Aadhaar number | Without meeting you: capped deposits and small term loans only, for up to one year (para 25, see below) |
| Aadhaar biometric e-KYC | Biometric authentication, including Aadhaar Face Authentication, done by a bank official, business correspondent or business facilitator (para 23, Explanation 2) | Banks, at a branch or with an agent | None in the Directions; full KYC |
| Offline Aadhaar verification | You share a UIDAI-signed Aadhaar paperless offline e-KYC XML file, which carries a reference ID instead of your Aadhaar number, or the Aadhaar Secure QR code; the bank verifies it offline, without Aadhaar authentication (paras 5(1)(xv) and 23(2)) | Any bank; useful when you do not want to share the Aadhaar number | None in person or inside V-CIP; for V-CIP the file must be no more than three working days old (para 27(2)(viii)). Used remotely without V-CIP, it is non-face-to-face onboarding (para 5(2)(x)), so the para 44 checks apply |
| DigiLocker (equivalent e-document) | The bank checks the issuer's digital signature on a document in your DigiLocker and takes a live photo (paras 5(1)(x) and 23) | Remote or branch onboarding | Remote use counts as non-face-to-face: extra checks apply (para 44) |
| CKYC | You give your KYC Identifier and consent; the bank downloads your record from the Central KYC Records Registry (CKYCR) and usually need not ask for the same documents again (paras 23(4) and 65(10)) | Anyone with a CKYCR record, except one from an account opened by OTP e-KYC without meeting the customer (para 25(8)) | Remote use: extra checks apply (para 44) |
| Digital KYC | How a bank records an in-person check of your original document (para 23): an officer's app takes a live photo of you and your original document, watermarked with GPS, time and the officer's ID; an OTP to your mobile counts as your signature on the form (para 24(9)) | In person: you and the officer meet (para 24(3)) | None; full KYC |
| Video KYC (Video-based Customer Identification Process, V-CIP) | A trained bank official verifies you on a live, recorded video call, using Aadhaar OTP e-KYC, offline Aadhaar, CKYC or a DigiLocker document, and checks your PAN (paras 26 and 27) | Remote onboarding and KYC updates | None; treated on par with face-to-face KYC, and the account becomes operational only after a concurrent audit (para 27(2)(xv)) |
Where you do not submit an e-document, some classes of regulated entities may still take a certified paper copy and photo instead of digital KYC, until a date the Government notifies (para 23, proviso).
For the full V-CIP rules, read our guide to what V-CIP is and how video KYC works. For the wider rule set, see the RBI KYC guidelines explained. This guide follows the RBI rules for banks; insurers and stockbrokers follow their own regulator's KYC rules (see the IRDAI video-based identification process (VBIP) guide and our guide to in-person verification (IPV) for SEBI-registered intermediaries).
What is full KYC, and how is it different from limited KYC?
Full KYC means the bank has completed customer due diligence (CDD) under para 23 or through V-CIP, so your account carries no KYC-based caps. The RBI text uses the term (para 29) without defining it. "Limited KYC" is this guide's label, not an RBI term, for an account opened through a route with caps until you complete full KYC.
| Account | Limits | How to move to full KYC |
|---|---|---|
| Opened with Aadhaar OTP e-KYC without meeting you (para 25) | Total balance in all deposit accounts up to ₹1 lakh; total credits up to ₹2 lakh in a financial year; term loans only, up to ₹60,000 a year; only one such account across all regulated entities (para 25(8)) | Complete KYC under para 23 or V-CIP within one year, or the bank closes deposit accounts and stops debits on loans (para 25(6) and (7)) |
| Small account, banks only (para 28) | Credits up to ₹1 lakh a year, withdrawals and transfers up to ₹10,000 a month, balance up to ₹50,000; no foreign remittances until full KYC | Complete KYC under para 23 or V-CIP; the account runs for 12 months, plus 12 more if you show you applied for an OVD (para 28(4)(v), (viii) and (ix)) |
| Small (minimum-detail) prepaid payment instrument (PPI), such as a wallet | At least an OTP-verified mobile and a self-declared ID number; up to ₹10,000 outstanding; no cash withdrawal or fund transfer | A small PPI with cash loading must become a full-KYC PPI (up to ₹2 lakh outstanding) within 24 months, or it takes no further credit; V-CIP can be used (PPI Master Directions paras 9.1(i) and 9.2) |
The PPI row comes from the RBI Master Directions on Prepaid Payment Instruments, which use the term "full-KYC PPI".
e-KYC vs CKYC vs video KYC: what is the difference?
e-KYC verifies you, CKYC stores your KYC record, and video KYC completes KYC remotely on a live call.
| Term | What it is | Its job |
|---|---|---|
| e-KYC (electronic KYC) | Aadhaar verification through UIDAI by OTP or biometrics | Verifies who you are |
| CKYC (Central KYC) | Your record in CKYCR, which the Central Registry of Securitisation Asset Reconstruction and Security Interest of India (CERSAI) runs (para 65(1)) | Lets other regulated entities reuse your KYC with your KYC Identifier |
| Video KYC (V-CIP) | A live, recorded video call with a trained bank official | Completes KYC without a branch visit |
The three often work together. In a V-CIP call, the official records the video and takes your identity details from one of the sources in the first table (para 27(2)(vi)). The bank then uploads the KYC record to CKYCR within 10 days of the account relationship starting (para 65(2)).
Which KYC route works without a branch visit?
Remote onboarding mainly works through three kinds of route: video KYC (V-CIP), Aadhaar OTP e-KYC, and records such as CKYC, DigiLocker, other e-documents or an offline Aadhaar file. Among remote routes, only V-CIP gives full KYC with no caps or extra non-face-to-face checks.
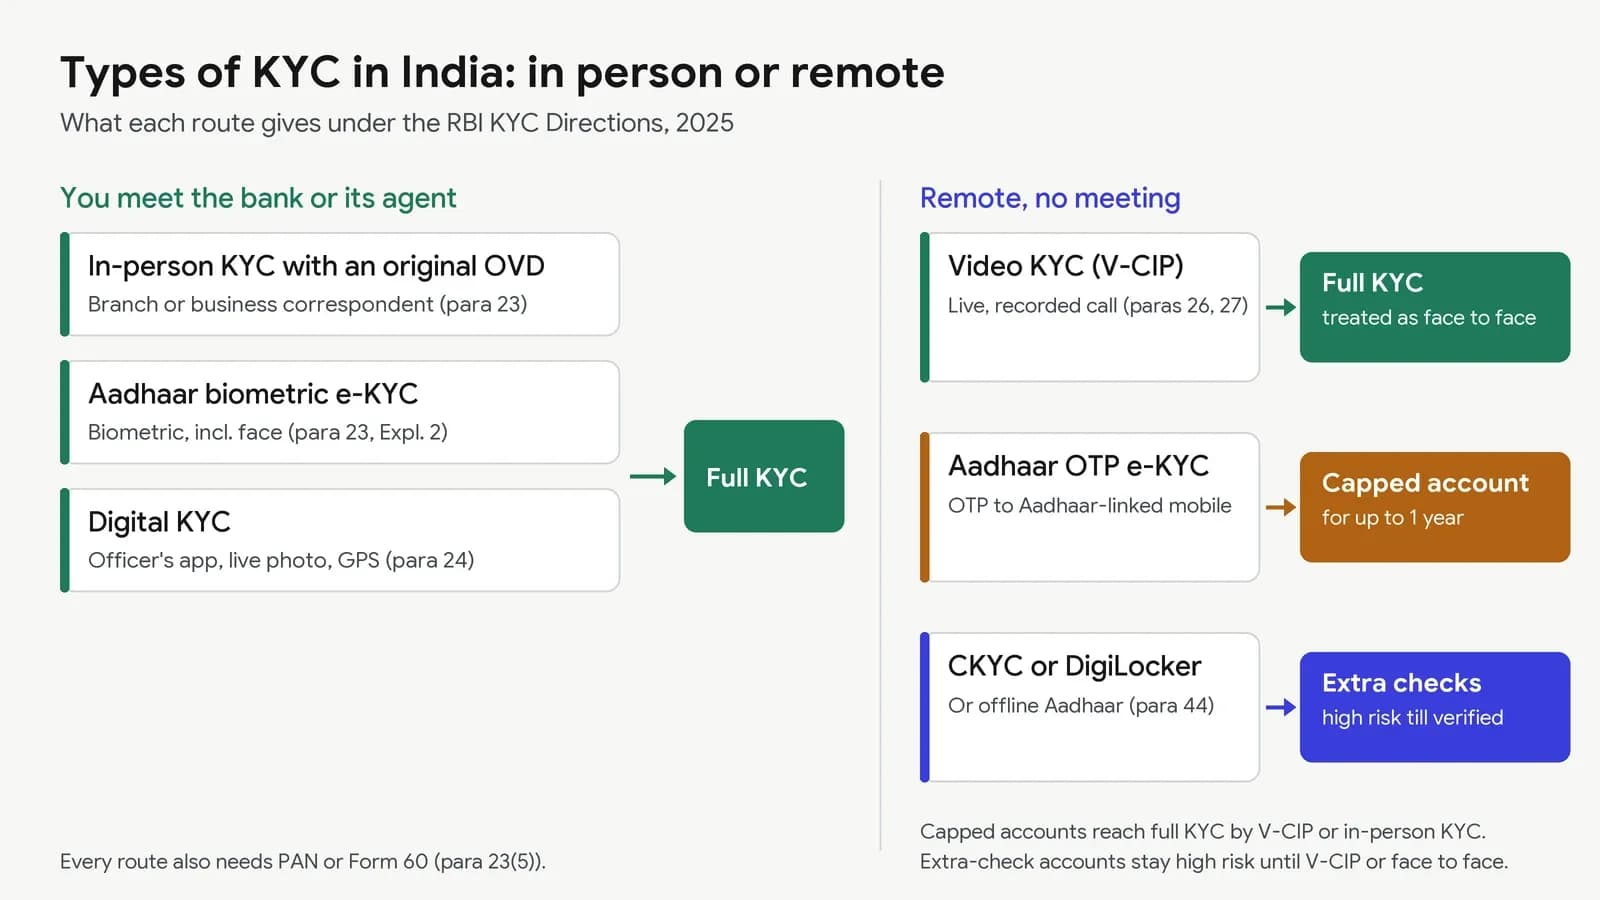
- V-CIP: on par with face-to-face KYC. A bank that offers V-CIP must make it the first option for remote onboarding outside the Aadhaar OTP route (para 44(1)).
- Aadhaar OTP e-KYC, remote: capped for up to one year; V-CIP lifts the caps without a branch visit (para 25(6)).
- CKYC, DigiLocker, other e-documents or offline Aadhaar, remote: allowed, but the bank must apply enhanced due diligence. It verifies your current address and PAN, and the first credit must come from your existing KYC-compliant bank account. You stay a high-risk customer until the bank verifies you face to face or by V-CIP (para 44(3) to (6)).
A video personal discussion (PD) is a lender's credit-assessment call, separate from KYC. Non-banking financial companies (NBFCs) follow their own KYC Directions, with the same Aadhaar OTP e-KYC limits: see video KYC for NBFCs.
How often must KYC be updated?
Banks must update KYC at least every two years for high-risk customers, every eight years for medium-risk and every 10 years for low-risk customers (para 42(1)). If nothing has changed and the bank already holds documents that meet current standards, a self-declaration by registered email, mobile, ATM or the bank's app is enough (paras 42(3)(i) and 42(5)(i)). Banks may use Aadhaar OTP e-KYC for an update without meeting you, and the para 25 caps do not apply to updates (para 42(3)(vi)).
FAQ: types of KYC in India
How many types of KYC are there in India?
The RBI gives no official number. Most guides name five: physical KYC, e-KYC, digital KYC, CKYC and video KYC. This guide counts eight routes in the RBI KYC Directions, 2025, because Aadhaar e-KYC splits into OTP, biometric and offline verification, and DigiLocker e-documents count on their own.
What are the steps in the KYC process?
You give proof of identity and address (an OVD, Aadhaar or your KYC Identifier) plus PAN or Form 60 (para 23). The bank verifies it through one of the routes above, uploads your record to CKYCR within 10 days of opening the account (para 65(2)), and updates it every two, eight or 10 years depending on your risk level (para 42(1)).
What is e-KYC, and what is its full form?
e-KYC stands for electronic Know Your Customer. In India it usually means Aadhaar e-KYC: the bank verifies you through UIDAI by OTP or biometrics instead of collecting paper copies.
What is the CKYC full form, and what is a KYC Identifier?
CKYC stands for Central KYC; your record sits in the Central KYC Records Registry (CKYCR). Your KYC Identifier, also called the CKYC number, has 14 digits under the CKYCR Operating Guidelines, and the bank must share it with you once it is generated (para 65(7)). You can find it on the CKYCR portal.
Is Aadhaar mandatory for KYC?
No. Aadhaar is not mandatory for KYC; you must give it only if you want a government benefit or subsidy under a notified scheme, and otherwise may share it voluntarily (para 23, Explanation 4). You can use another OVD, such as a passport, driving licence or voter ID.
What is digital KYC, and is it the same as video KYC?
Digital KYC, in RBI terms, is an in-person process: a bank officer's app captures your live photo and original document, watermarked with GPS and time (para 24). Many people use the words for any online KYC. It is not video KYC, which is a remote, recorded video call with a bank official (paras 26 and 27).
Building V-CIP into your bank or fintech app? Sign up for VideoSDK to get API keys; a new account comes with a $20 credit.